
Column
Cheap Intelligence Can Still Produce Expensive Work
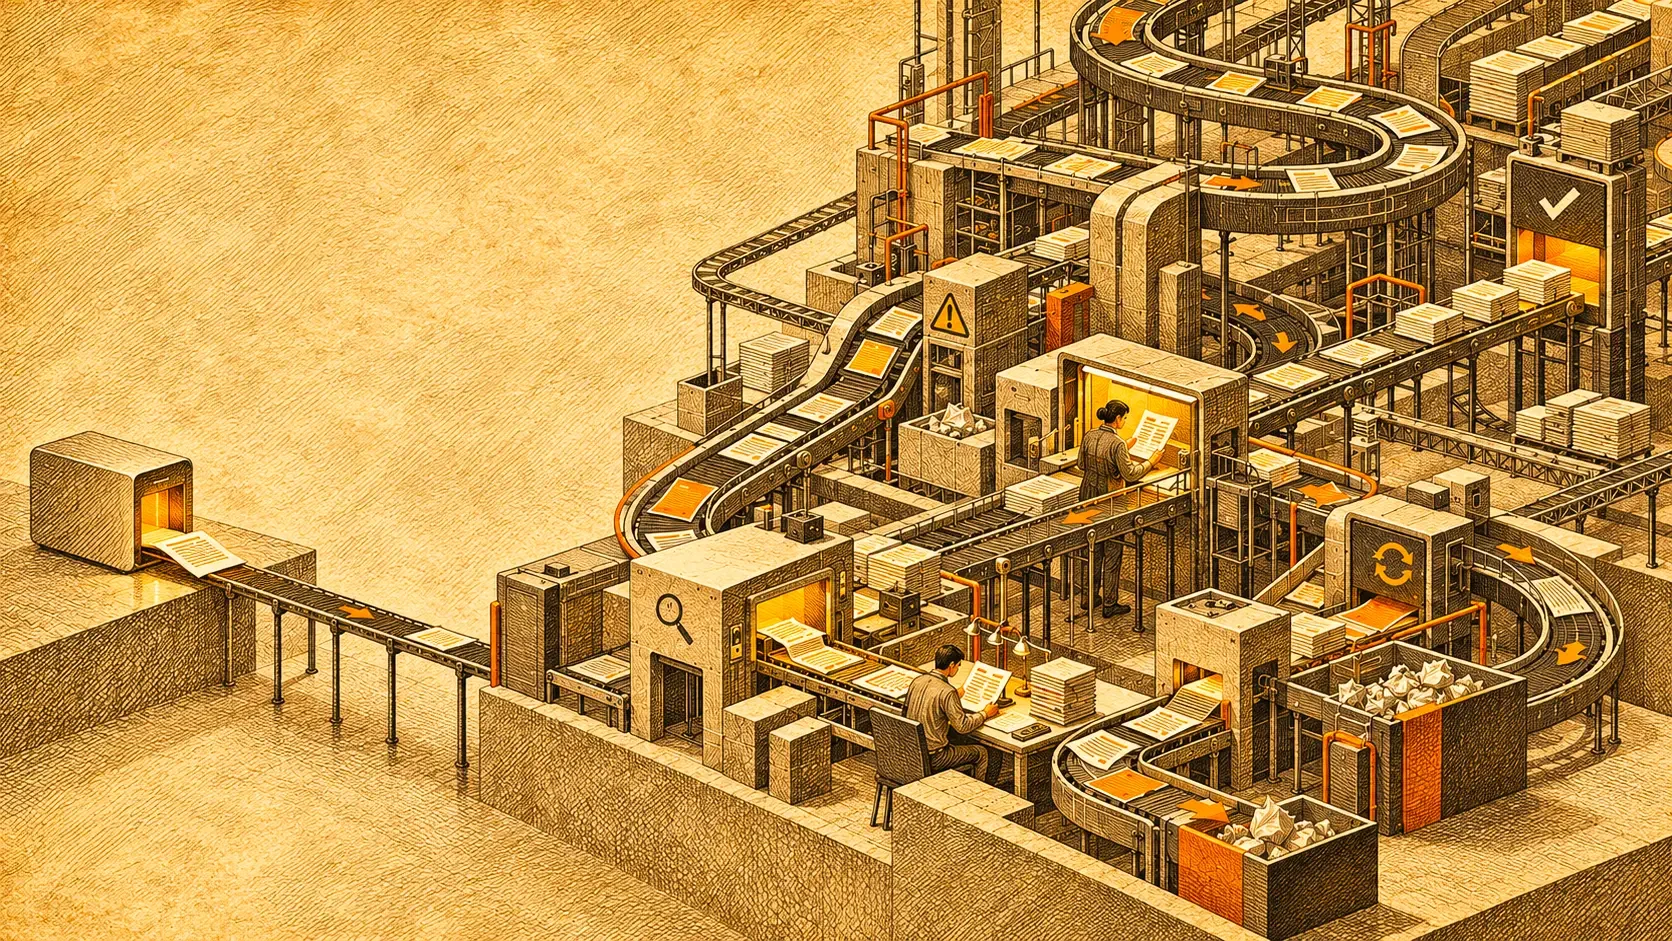
The article argues that AI economics should be measured by cost per accepted outcome, not tokens or API calls. A cheap model can still produce expensive work once human review, retries, verification, external tools, and correction are included. Conversely, a more expensive system may be economically superior if it eliminates enough labor or resolves complex tasks more reliably. The relevant question is therefore what the business spends to obtain work that actually meets its standard.
Agentic AI adds another complication because execution costs can vary sharply across similar tasks. Agents decide how much reasoning, searching, tool use, and retrying to perform, creating unit-cost uncertainty that averages can conceal. The article distinguishes technical efficiency from economic efficiency and argues that enterprises should give agents enough discretion to create value while imposing budgets, tool limits, verification rules, and stopping conditions that prevent unproductive spending.

The Borrowers Who Never Ask
The article argues that observed demand reflects not only people’s needs, but also their expectations about whether participating is worthwhile. New York Fed data show this distinction clearly: discouraged non-application fell between February and June 2026, while rejection among actual applicants barely changed. These measures capture different stages of the market, and looking only at applicants can miss people who needed credit but never tried because they expected rejection.
The broader issue is selection. A business sees inquiries, applications and conversions only after potential customers decide to enter the process. Someone who expects a service to be unaffordable may never request a quote, leaving no trace in company data. The piece argues that research should therefore examine expectations before participation, distinguishing genuine barriers from mistaken beliefs and asking what information might change the decision to engage.

What Agentic AI Actually Changes
The article argues that the core economic feature of agentic AI is discretion. Unlike traditional automation, agents can interpret objectives, choose tools, revise plans and decide when a task is complete. That flexibility creates value because it lets software handle ambiguity and exceptions, but it also makes costs less predictable as reasoning, tool use, retries, verification and human review vary across tasks.
The relevant metric therefore shifts from cost per model call to cost per completed objective. The piece introduces an “autonomy frontier”: additional discretion helps until its value begins to flatten while compute costs, latency and operational risk keep rising. The goal is not maximum autonomy, but the right authority for the task. Enterprises should define tool access, spending limits, approval points, verification and escalation rules, treating agent design as an economics-of-delegation problem before an architecture problem.

More Agreement, Less Certainty
The article argues that inflation expectations cannot be understood from a single headline forecast. In August, New York Fed data showed households’ year-ahead forecasts moving closer together even as the uncertainty within individual forecasts widened. Disagreement and uncertainty therefore capture different things: one measures how far people are from each other, while the other measures how wide a range of outcomes each person considers plausible.
That distinction matters for decisions. People can agree on the central outlook while remaining hesitant because they still see substantial downside risk. For firms, the same logic applies to investment and planning, especially when commitments are costly to reverse. Research can therefore create value without materially changing the headline forecast if it narrows the plausible range enough to alter timing, scale, or reversibility. The piece concludes that forecasts should be discussed alongside the uncertainty around them.

What Would You Do Differently If You Knew?
The article argues that research creates value only when information can change a decision, either immediately or through follow-up choices. In a launch example, one customer study is worth $18,000 when favorable and unfavorable results lead to different actions. But when prior confidence is low enough that neither result changes the launch decision, the same study has negative standalone value.
That changes once research becomes sequential. Using backward induction, the model shows that evidence insufficient after one study can still be valuable because it affects whether another study is worth buying. Research therefore has option value, and the optimal stopping point depends on beliefs, signal quality, costs, and available actions. The practical lesson is to define the decision before commissioning more analysis and stop only when further information no longer changes the best action or next worthwhile question.

Thoughts on the Economics of Memory
The article argues that advertising is often misunderstood as persuasion or information when one of its most important effects is memory retrieval. Ads can make a product, brand, or category easier to recall when a buying situation arises. Recent research on “ads as cues” shows that advertising can increase demand among habitual users and even spill over to similar competitors, as when one cola ad reminds consumers of the broader cola category.
The piece uses this mechanism to clarify brand versus performance marketing. Upper-funnel ads may not create immediate action, but they can make later search, sales, or product interactions more effective by making the brand more retrievable. The measurement challenge is therefore about the estimand: a brand-level experiment can estimate marginal lift, but not what advertising does to the full competitive memory environment.

When Economic Pain Fails to Buy Political Compliance
The article argues that sanctions are effective at imposing economic and technological costs, but much less reliable at forcing political compliance. Iran’s experience shows the distinction: severe GDP losses and financial isolation helped create leverage for the JCPOA, but only because pressure was paired with negotiated sanctions relief and a defined off-ramp. Sanctions work best when demands are limited, dependence is high, substitutes are scarce, pressure is fast and compliance is credible.
It warns that prolonged pressure can lose coercive power as targets adapt through rerouting, shell firms, friendly intermediaries and smuggling networks, while civilians often bear unequal costs. Sanctions can still degrade capabilities, especially through finance and technology controls, even when leaders refuse to change core security policies. The piece concludes that economic coercion works as leverage and containment, not as a machine for changing what states consider vital.

AI Exposure Is Highest Where the Desks Are
The article argues that AI’s first automation shock is likely to hit richer economies harder because their labor markets contain more clerical, professional and digital work. Developing economies face lower immediate exposure, but that is not pure protection. It often reflects weaker electricity, connectivity, institutions and managerial capacity, which limit their ability to turn AI adoption into productivity gains.
Using the proposed Google data center hub in Visakhapatnam as a test case, the piece warns that hosting compute is not the same as building technological sovereignty. Data centers can bring infrastructure, jobs and cloud access, but they also consume scarce power, water and public concessions. The article argues developing economies should prioritize adoption and adaptation before frontier imitation, approving large AI infrastructure only when it leaves behind durable capability, local value capture and broad economic benefit.

The Melt-Up Is an Information Problem
The article argues that the 2026 AI-led equity melt-up is best understood as an information cascade, not simple euphoria. In a cascade, investors observe others buying and rationally discount their own private signals, so price gains, heavy volume and low volatility can look like conviction while actually reflecting suppressed disagreement. That makes the market appear stable precisely when it may be informationally fragile.
It distinguishes melt-ups from bubbles: a melt-up is rapid price appreciation that can become a bubble if fundamentals fail to catch up, but current AI enthusiasm still has some earnings support. The risk is that price begins aggregating imitation rather than information. July earnings shocks show how quickly a cascade can break once investors start processing fundamentals again. The key signal is whether new information still moves prices.

Should the AI Boom Pay Its Way?
The article argues that the AI boom has physical public costs that should not be quietly shifted onto households and municipalities. Data centers require electricity, transmission, substations, water, land, and cooling infrastructure, while a small group of firms captures much of the upside. The case is not to stop AI investment, but to make developers pay for attributable grid, water, and local infrastructure costs in exchange for faster, clearer approvals.
It also proposes a modest, independently governed sovereign wealth fund funded by AI-linked public revenues or infrastructure-use levies. The fund would diversify public exposure, preserve fiscal capacity, and support underprovided capabilities like public-interest compute, cybersecurity and worker-transition pathways. The broader bargain is to trade a little short-term speed for better cost allocation, stronger workplace safeguards, and a public balance sheet that lets households share in AI-driven wealth.

The 114-Word Central Bank
The article argues that Kevin Warsh’s 114-word June FOMC statement marks a deliberate break from the post-2008 era of expansive Fed communication. Using Sims’s rational inattention framework, it explains why longer statements never meaningfully reached ordinary households. Most people process Fed communication through a narrow channel, reducing complex guidance to a basic directional signal about rates, inflation or mortgage costs.
The effects of shorter communication are therefore asymmetric. For households, little changes because the removed detail was never absorbed. For markets and professional Fed-watchers, the withdrawal matters because high-capacity audiences scrutinize every word, shifting attention to press conferences, minutes and speeches. The article extends the logic to news feeds, arguing that falling engagement reflects rational bandwidth management in a noisy policy environment. Shorter is not dumber, but simplicity must not become silence.

The Fed’s Balance-Sheet Fight Is Bigger Than One Rate Decision
The article argues that Warsh’s first major Fed signal was not the June rate hold but his task force reviewing the Fed’s balance-sheet framework. After QT ended in late 2025 and reserves reached the ample-reserves floor, the fight shifted from runoff speed to the operating system of post-2008 monetary policy. The balance sheet affects duration risk, term premia, repo markets, bank reserves, mortgage finance and the Fed’s ability to control short rates.
It presents the case for a smaller portfolio: fewer distortions, clearer fiscal-monetary boundaries, less political exposure and more room for future crisis response. But shrinking too far risks plumbing failures, as 2019 repo stress showed. Reserve demand, payment needs and repo capacity may bind before policymakers expect. The piece concludes that Warsh’s test is disciplined redesign, not ideological shrinkage; balance-sheet policy now sits at the core of monetary policy.